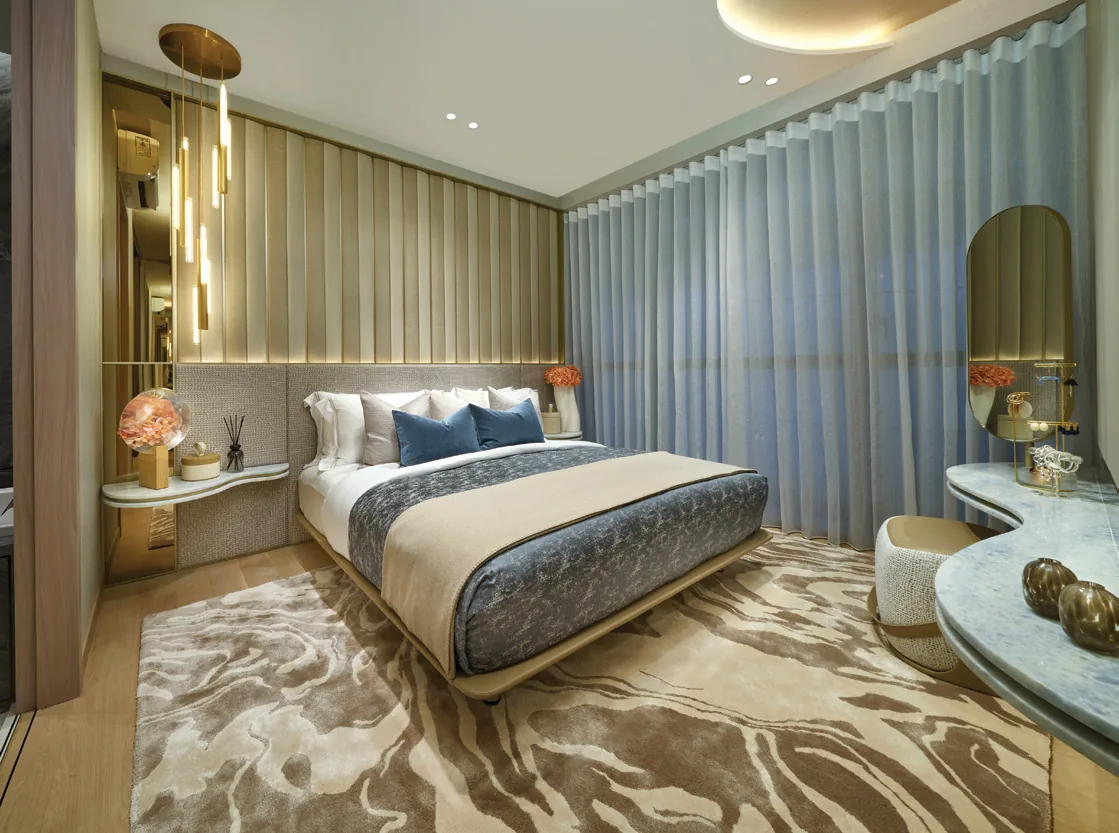
 For illustration only
Buying at Union Square Residences in One Line
Anyone can buy. Union Square Residences is a private condominium within a mixed-use development, so there is no income ceiling, no citizenship requirement and no minimum occupation period. Singapore Citizens, Permanent Residents, foreigners and companies may all purchase a unit.
What changes from buyer to buyer is the cost. Additional Buyer’s Stamp Duty depends on residency and on the homes already owned, and the loan limits depend on the loans already outstanding. This article sets out the position as at October 2026.
Why Union Square Residences Is Open to All Buyers
The homes are strata condominium units on a 99-year lease that began on 11 October 2024. The Residential Property Act lets foreigners buy condominium units without the approval most landed homes require, which is why the launch-day buyers included Permanent Residents and foreigners from several countries.
Because the tower is private housing, none of the public-housing conditions apply. A buyer may own other property, need not form a family nucleus, and may lease the unit out once it is completed, subject only to stamp duty and the usual tenancy rules.
Who Bought at the Union Square Residences Launch
CDL reported that about 83% of launch-day buyers were Singaporeans, with the remaining 17% made up of Permanent Residents from China, Malaysia, the United Kingdom and the Netherlands, and foreigners from Norway and the United States.
The one-bedroom, two-bedroom and three-bedroom premium types were the most popular on the day, and the level-38 Sky Suite was among the 75 homes sold. EdgeProp later reported that a Singapore Permanent Resident bought the penthouse in February 2026.
ABSD for Each Union Square Residences Buyer
Additional Buyer’s Stamp Duty is charged on top of Buyer’s Stamp Duty. As at October 2026, IRAS charges Singapore Citizens 0% on a first residential property, 20% on a second and 30% on a third or more; Permanent Residents 5%, 30% and 35%; foreigners 60%; and entities 65%.
Buyer’s Stamp Duty is the same for every buyer on the same purchase figure. ABSD is where profiles differ: nothing for a Citizen buying a first home, 5% for a Permanent Resident buying a first home and 60% for a foreign buyer. The stamp duty page works an illustrative example through.
Treaty Nationals and Couples at Union Square Residences
Singapore’s free trade agreements give nationals and permanent residents of the United States, and nationals of Iceland, Liechtenstein, Norway and Switzerland, the same ABSD treatment as Singapore Citizens. A buyer from one of those countries buying a first home pays the Citizen rate of 0%.
Where several people buy together, the highest rate among them generally applies to the whole price. Married couples with at least one Citizen spouse, buying their first home together, may apply for remission; IRAS decides each case on its facts.
Upgraders Considering Union Square Residences
Many buyers of city-fringe homes already own a flat or condominium elsewhere. If they still own it when they sign for a unit at Union Square Residences, a Citizen pays 20% ABSD on the second property and a Permanent Resident 30%.
A married couple who sell their first home within the period IRAS allows can apply for a refund, but the duty is still paid within 14 days of signing, so the cash has to be found at the start. The stamp duty page sets out the rates.
Companies and Trusts at Union Square Residences
Buying through a company or a trust is possible, but rarely the cheaper route for a home. Entities pay 65% ABSD, and a company borrowing to buy residential property is assessed on its own finances, so most households buy in their own names.
Families planning for succession sometimes ask about holding a home in trust. Trustees generally pay ABSD at the entity rate, with limited exceptions published by IRAS, so the structure is best settled with a lawyer before any commitment.
Financing for Each Union Square Residences Buyer
The MAS loan rules apply to everyone. A borrower with no outstanding housing loan may borrow up to 75% of the price, with one outstanding loan 45% and with two or more 35%, and lower limits apply where the tenure passes 30 years or the loan runs beyond age 65.
Citizens and Permanent Residents may use CPF Ordinary Account savings within CPF rules; foreigners pay their share in cash. The housing loan page explains the limits and the TDSR calculator sizes the loan.
Next Steps at Union Square Residences
Because the duty depends on who buys, the names on the purchase and the order of selling and buying are worth settling before choosing a unit. The price list shows what each home costs; the buyer’s profile decides the total cost.
The Sales Concierge sends the current price list and the homes still available at Union Square Residences. Showflat viewings are arranged by appointment through the Sales Concierge.
This article is general information as at the date shown and is not financial, legal or tax advice. Statutory figures are from IRAS and MAS; particulars of Union Square Residences are from the developer’s brochure and announcements, and sales figures from published caveat reports.
Talk to the Union Square Residences Sales Concierge
The Sales Concierge sends the price list on request, the balance units and the e-brochure for Union Square Residences. Showflat viewings are arranged by appointment through the Sales Concierge.